

Instant Borrow - Cash Now
by LM GROUPS
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
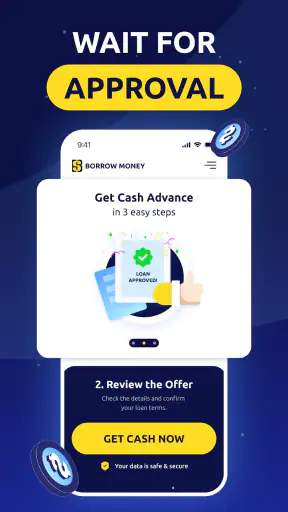
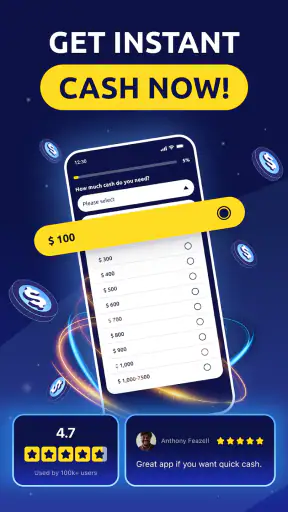
 Analysis by Getfullapps
When money gets tight inside a household, the hardest part is often not finding a possible borrowing option; it is keeping everyone clear about what is being requested, why it is needed, and what repayment will mean later. I tested Instant Borrow - Cash Now with that practical situation in mind. It is a free finance app from LM GROUPS, designed around urgent borrowing rather than everyday budgeting or long-term financial planning. My first impression is that it aims to reduce the delay and stress around a short-term cash need, but it should be treated as a borrowing tool, not as extra income.
The app has attracted a 4.7 average from around 26K ratings and has passed 500K installs, which suggests that many people are at least willing to try this kind of service. It is also marked for Everyone, although that label should not be confused with a recommendation for every age group to borrow money. The current release is version 1.0.5, and the app runs on Android 7.0 or later. Those details make it accessible to many older Android devices, but the more important question is whether it fits the way you and the people you live with handle financial decisions.
How Instant Borrow works in a shared household
A realistic example is a household where one person discovers an urgent expense just before payday. Perhaps a utility bill, transport cost, or necessary purchase cannot wait. The person who owns the phone may open the app to explore a borrowing route, while a partner or another trusted adult wants to understand the decision before money is requested. In that situation, the app can be useful as a starting point for a quick conversation, but it should not become a substitute for that conversation.
I would not install it on a shared phone and assume that everyone can safely use the same session. Financial apps are personal by nature. A household may share a device, but that does not mean it shares one financial identity. Before anyone begins, I would decide whose account is being used, whose information is being entered, and who would ultimately be responsible for repayment. That simple boundary prevents a surprisingly common problem: one person starts an application casually, while another assumes the request belongs to them.
The strongest use case is a single adult handling their own urgent expense while keeping a trusted household member informed. The weaker use case is a group trying to manage several people’s needs from one phone. Instant Borrow - Cash Now is not something I would treat as a household wallet, a family budget board, or a shared emergency fund. Its purpose is narrower, and keeping that purpose narrow makes the experience easier to control.
There is also a useful distinction between checking an option and committing to it. If I were helping someone use the app, I would first write down the expense, the amount genuinely needed, and the date when repayment could realistically happen. Only then would I open the borrowing flow. This avoids the temptation to request more simply because the process feels immediate. The app’s convenience is valuable, but convenience can also make an unnecessary loan feel harmless.
Setting clear boundaries before opening the app
On a shared device, I would begin by closing unrelated financial apps and making sure the person using Instant Borrow - Cash Now is the correct account holder. I would also avoid saving personal details in a place where another household member can casually access them. That is not a special feature of this app; it is basic digital hygiene, and it matters more when phones are passed between partners, parents, adult children, or roommates.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
My next boundary would be purpose. I would use the app for one defined short-term need, not for a general shopping session. A useful note might say, “transport and groceries until payday,” rather than “extra cash.” The first description creates a limit. The second leaves the door open to borrowing beyond the original problem. This small habit is one of the most practical ways to keep an urgent borrowing app from becoming part of a recurring cycle.
I would also keep the application process separate from a child’s profile or a teen’s casual access to the phone. The Everyone content label describes the app’s store classification, not a child’s ability to make responsible credit decisions. In a family setting, an adult should control the financial decision and explain that opening an app does not make borrowing free, risk-free, or consequence-free.
Another boundary concerns notifications and visibility. If several people use the same handset, I would check who can see alerts, messages, or account screens before entering financial information. I would not leave the app open on a kitchen table or lend the unlocked phone to someone while a borrowing screen is active. These are ordinary precautions, but they are especially important when the device is shared more freely than the finances are.
For people using an older Android phone, the minimum requirement of Android 7.0 is helpful because it does not force an upgrade to a recent device simply to install the app. Still, an older phone may be used by more than one person or have limited security support. In that case, I would be more careful about screen locks, software updates, and who can access the device. Compatibility makes installation possible; it does not remove the responsibility to protect the account.
Coordinating the decision instead of hiding it
Household coordination is where I think the app needs the most sensible human support. If borrowing affects shared bills, I would tell the other responsible adult before submitting anything. The discussion does not need to be dramatic. It can cover three direct questions: what is the money for, when is repayment expected, and what household expense might be reduced if repayment is harder than planned?
That last question is easy to overlook. People often think only about receiving the money, while the later payment competes with rent, food, transport, or another bill. I would put the expected repayment beside the household’s existing commitments before deciding. If the numbers leave no comfortable room, a slower alternative may be safer even if it is less convenient.
Instant Borrow - Cash Now is more relevant than a traditional bank appointment when timing is the main problem. A bank account, a credit union, an employer advance, or help from a trusted person may involve more waiting or conversation, but those routes can be better when the need is larger, the repayment period is longer, or the borrower wants a relationship they already understand. The app’s appeal is speed and simplicity, not a guarantee that it is the cheapest or most suitable option in every case.
I would also compare the app with ordinary overdraft access or an existing credit facility rather than assuming the newest option is best. A familiar product may have clearer terms for someone who already uses it. On the other hand, a person without a convenient traditional option may value the ability to investigate an urgent borrowing possibility from a phone. The right comparison is not “modern versus old-fashioned”; it is clarity, total repayment, timing, and the consequences of missing a payment.
One practical technique is to keep a small written record after the decision. I would note the requested amount, the purpose, the expected repayment date, and who in the household knows about it. I would not rely on memory, especially when several bills are due at once. This record is not a feature I am claiming the app provides; it is a workflow I recommend because quick borrowing can otherwise disappear into everyday spending.
Another useful trade-off is speed versus review time. An urgent situation may justify moving quickly, but I would still pause long enough to read every screen and understand the commitment before confirming. If the app presents an offer or repayment information, I would check the total cost rather than focusing only on the amount arriving. A fast application is helpful only when the borrower understands what follows it.
Age, trust, and personal responsibility
The app’s Everyone rating can make it look broadly approachable, but borrowing money is an adult responsibility in practical terms. I would never let a child or young teenager explore the app as if it were a normal shopping or entertainment application. Even when a young person is the one who notices the household need, an adult should make the financial decision and own the consequences.
For older teenagers, the conversation can be educational without turning the phone into a shared account. I would explain the difference between an application, an approval, and money that must later be repaid. I would also make clear that a high store rating does not mean every borrower receives the same result or that the service is automatically right for a particular situation. Ratings describe user sentiment; they do not replace personal affordability checks.
Trust matters between adults too. A partner should not use another person’s details merely because the phone is available, and a roommate should not assume that shared rent creates permission to borrow in someone else’s name. If the device belongs to one person but the financial need belongs to another, I would stop and establish whose account and responsibility are involved before continuing.
This is also why I would avoid presenting the app as emergency household insurance. It may help someone explore a way to cover an urgent expense, but repeated reliance on borrowing can point to a deeper budget problem. If the same type of shortfall happens every month, a budgeting review, bill negotiation, community assistance, or a conversation with a financial counselor may be more useful than another quick application.
People who should probably skip it include anyone who cannot identify a realistic repayment source, anyone already juggling several short-term debts, and anyone who feels pressured by a partner or family member to apply. The app may be free to install, but borrowing itself should never be evaluated by the download price alone. A person who needs more time to compare options is not failing; they may be protecting themselves from a decision made under stress.
Where the app fits among familiar alternatives
Compared with a spreadsheet or budgeting app, Instant Borrow - Cash Now is aimed at access to funds rather than helping you understand spending patterns. A budget tool is better for finding why money runs short and preventing the next crisis. Compared with a bank, the app is more convenient for someone who wants to begin from a mobile device, but a bank or credit union may feel more transparent to a borrower who already knows its process and terms.
Compared with borrowing from family, the app can avoid an uncomfortable personal request, but it also removes the flexibility that a trusted person might offer. A relative may agree to a different repayment date; a formal borrowing arrangement may not provide that same human adjustment. Compared with using a credit card, the app might appeal to someone without available credit, while an existing card could be simpler for a small purchase if its terms are already understood. None of these choices is universally best.
The app is most convincing when the expense is genuinely urgent, the amount is controlled, and the repayment plan is realistic. It is less convincing when someone is trying to fund discretionary spending, cover one debt with another, or make a large financial decision without time to read carefully. That distinction is more important than the app’s clean promise of speed.
I also see a household advantage in using it as a conversation trigger. Opening the app can prompt a couple to name the immediate problem and agree on a limit. But the app cannot create trust between them. If one person is hiding the application, using another person’s device or details, or avoiding questions about repayment, the underlying issue is not a missing feature. It is a boundary that should be resolved before any financial request proceeds.
My household verdict after using it
My overall view is cautious but positive. Instant Borrow - Cash Now is a focused finance app from LM GROUPS that may suit an adult who needs to investigate a short-term borrowing option without a long wait. Its free availability, broad device compatibility, and strong public reception make it easy to consider, while the current version, 1.0.5, shows that it is still sensible to read each screen carefully rather than assuming a familiar experience across every phone.
For a shared household, I would recommend it only with firm account boundaries. One adult should be the responsible applicant, personal information should stay private, and any borrowing that affects shared finances should be discussed before confirmation. I would keep a written repayment plan and compare the app with a bank, credit union, overdraft, existing credit, or trusted personal help before choosing.
The most important rule is simple: use the app to examine an urgent option, not to make an unaffordable expense look affordable. If you can explain the purpose, identify the repayment source, and make the decision without pressure, it may be a practical tool. If those answers are unclear, I would choose a slower and more transparent alternative instead. That is the point at which convenience stops helping and starts creating risk.
For the right person, this app can reduce the friction of exploring immediate financial help. For a household, though, its success depends less on the phone and more on honest coordination around it. I would recommend trying it only after agreeing who is using the account, what the money is for, and how repayment fits into the household plan. Used that way, Instant Borrow - Cash Now has a clear place among mobile borrowing options without pretending to solve every money problem.
Pros
- Quick application process with minimal paperwork
- Clear repayment terms shown before accepting an offer
- Useful for handling short-term, unexpected expenses
- Funds may arrive quickly after approval
- Simple interface makes loan details easy to review
Cons
- Approval and loan availability may vary by state or region
- Interest and fees can make borrowing expensive
- Late payments may lead to extra charges or credit damage
- Not suitable as a long-term solution for recurring expenses
- May require access to personal and financial information
FAQs for Instant Borrow - Cash Now
What is Instant Borrow - Cash Now, and how does it work?
Instant Borrow - Cash Now is a financial app designed to help eligible users explore short-term borrowing options through a mobile device. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can assess your request. Available loan amounts, repayment periods, approval decisions, and funding times can vary depending on your profile, location, and participating lenders.
Is Instant Borrow - Cash Now a direct lender?
Before submitting an application, users should carefully check whether Instant Borrow - Cash Now provides loans directly or operates as a lending marketplace or connection service. Some financial apps collect your information and forward it to third-party lenders, whose terms may differ considerably. Review the lender’s name, annual percentage rate, fees, repayment schedule, privacy policy, and authorization details before accepting any offer or sharing sensitive information.
How much does borrowing through the app cost?
The total cost depends on the offer you receive and may include interest, an annual percentage rate, origination charges, administrative fees, late-payment penalties, or other costs. Do not assume that an advertised amount or fast approval represents the final price. Read the complete loan agreement carefully and compare the total repayment amount with your budget before confirming the transaction.
How quickly can approved funds be received?
The app may promote quick access to funds, but approval and deposit timing are not guaranteed. Processing can depend on identity verification, application accuracy, lender review, banking hours, weekends, holidays, and the receiving institution. Even if an application is completed quickly, funding may take additional time. Check the final disclosure for the expected deposit date and any conditions.
What information and permissions does the app require?
A borrowing application may request details such as your legal name, address, date of birth, government identification information, income, employment, bank account, and contact details. Review every permission and privacy disclosure before proceeding, especially if the app requests access to contacts, messages, location, or device data. Only provide information through the official app or website, and avoid services that request upfront payment or unnecessary access.











